2019-09-19 15:30:00 Thu ET
federal reserve monetary policy treasury dollar employment inflation interest rate exchange rate macrofinance recession systemic risk economic growth central bank fomc greenback forward guidance euro capital global financial cycle credit cycle yield curve
U.S. yield curve inversion can be a sign but not a root cause of the next economic recession. Treasury yield curve inversion helps predict each of the U.S. recessions since the 1970s. However, no fundamental reason can help explain whether this inversion causes each recession. Correlation may not imply causation.
Many stock market analysts focus on the 3 root causes of an economic recession. First, the monetary authority tends to institute interest rate hikes to better contain inflation or money supply growth. A sustainable series of interest rate hikes help prevent macroeconomic instability; otherwise, high inflation would become a major source of economic disturbance.
Second, key energy prices often increase substantially in the dawn of an economic recession. Oil and natural gas prices tend to fluctuate due to geopolitical risks and military confrontations.
Third, stock market analysts would expect to see high unemployment, low capital investment, and low industrial production several months before a major recession. In this key alternative scenario, subpar labor and capital productivity can cause the economy to slide into at least 2 consecutive quarters of negative real GDP growth. Whether Treasury yield curve inversion serves as a sign but not a root cause of the next economic recession remains open to controversy.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2023-02-07 08:26:00 Tuesday ET
Michel De Vroey delves into the global history of macroeconomic theories from real business cycles to persistent monetary effects. Michel De Vroey (2016)
2023-09-07 11:30:00 Thursday ET
Michael Woodford provides the theoretical foundations of monetary policy rules in ever more efficient financial markets. Michael Woodford (2003)
2018-08-13 12:39:00 Monday ET
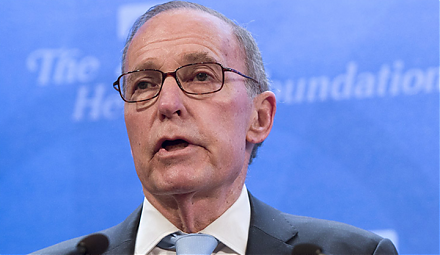
White House chief economic adviser Larry Kudlow points out that the recent U.S. dollar strength shows a clear sign of investor confidence and optimism. Gree
2022-09-15 11:38:00 Thursday ET
Capital structure choices for private firms The Kauffman Firm Survey (KFS) database provides comprehensive panel data on 5,000+ American private firms fr
2019-01-08 17:46:00 Tuesday ET
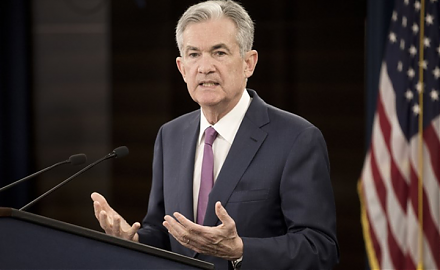
President Trump forces the Federal Reserve to normalize the current interest rate hike to signal its own monetary policy independence from the White House.
2017-04-01 06:40:00 Saturday ET
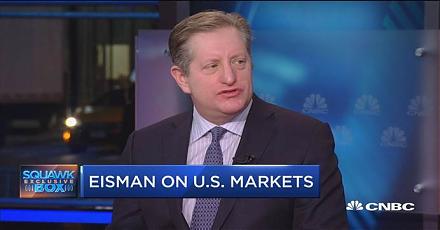
With the current interest rate hike, large banks and insurance companies are likely to benefit from higher equity risk premiums and interest rate spreads.