2019-09-09 20:38:00 Mon ET
federal reserve monetary policy treasury dollar employment inflation interest rate exchange rate macrofinance recession systemic risk economic growth central bank fomc greenback forward guidance euro capital global financial cycle credit cycle yield curve
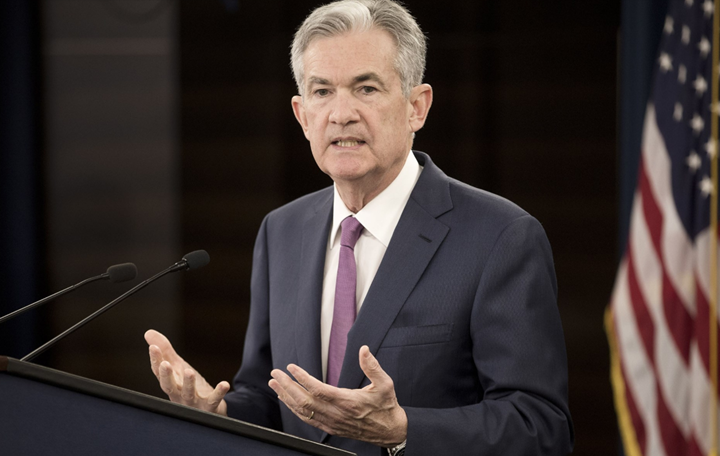
Harvard macrofinance professor Robert Barro sees no good reasons for the recent sudden reversal of U.S. monetary policy normalization. As Federal Reserve Chair Jerome Powell yields to the persistent demands of a vocal president, the FOMC approves an interim interest rate cut by quarter point to 2%-2.25%. This rate cut represents a clear departure from the current business cycle of interest rate hikes in recent years. Barro advocates the Taylor monetary policy rule that the nominal interest rate should rise in response to higher inflation and economic output both relative to their targets. In accordance with the key Taylor monetary policy rule, the nominal interest rate normally tends toward a gradual long-term equilibrium path.
In this light, Barro regards the recent interest rate reduction as a special deviation from the prior path of U.S. monetary policy normalization. Federal Reserve Chair Jerome Powell seems to justify the recent interest rate cut in terms of the fact that U.S. inflation remains low and tame as the economy operates near full employment despite continual trade escalation between the U.S. and China. Barro indicates the clear and present danger that the recent rate reduction represents a dovish Powell response to many stock market analysts and the Trump administration.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2020-11-03 08:30:00 Tuesday ET
Agile lean enterprises break down organizational silos to promote smart collaboration for better profitability and customer loyalty. Heidi Gardner (2017
2019-11-13 11:34:00 Wednesday ET
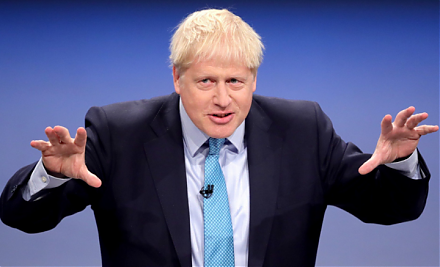
The new Brexit deal can boost British pound appreciation and economic optimism. British prime minister Boris Johnson wins the parliamentary vote on his new
2019-01-08 17:46:00 Tuesday ET
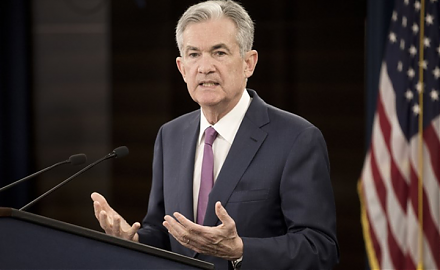
President Trump forces the Federal Reserve to normalize the current interest rate hike to signal its own monetary policy independence from the White House.
2019-01-02 06:28:00 Wednesday ET
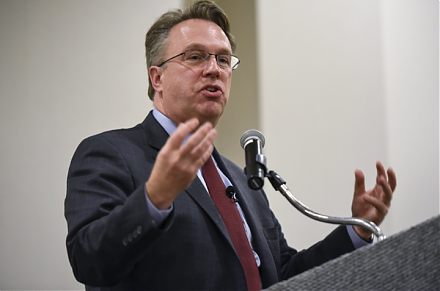
New York Fed CEO John Williams listens to sharp share price declines as part of the data-dependent interest rate policy. The Federal Reserve can respond to
2018-07-09 09:39:00 Monday ET
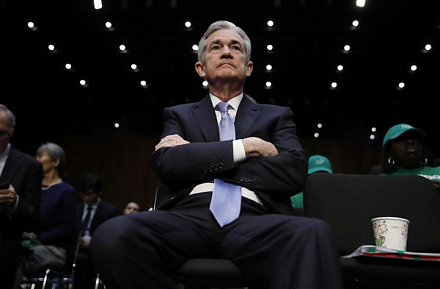
The Federal Reserve raises the interest rate again in mid-2018 in response to 2% inflation and wage growth. The current neutral interest rate hike neither b
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla