
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 3 October 2026
2019-12-16 11:37:00 Monday ET
America and China cannot decouple decades of long-term collaboration in trade, finance, and technology. In recent times, some economists claim that China ma
2024-07-31 09:28:00 Wednesday ET
In the modern monetary system, each new CBDC helps anchor public trust in money in support of economic welfare, especially in a cashless society. In our
2018-03-23 08:26:00 Friday ET
Personal finance and investment author Thomas Corley studies and shares the rich habits of self-made millionaires. Corley has spent 5 years studying the dai
2025-09-21 12:32:00 Sunday ET
Stock Synopsis: With a new Python program, we use, adapt, apply, and leverage each of the mainstream Gemini Gen AI models to conduct this comprehensive fund
2019-01-01 03:34:48 Tuesday ET
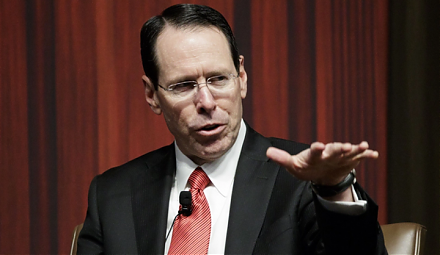
American allies assist AT&T and Verizon in implementing 5G telecommunication technology in the U.S. as such allies ban the use of HuaWei 5G telecom equi
2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode
 Reports
 Metrics
 Events

 AI Stock Synopses