Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 17 October 2026
2019-02-28 12:39:00 Thursday ET
New York Fed CEO John Williams sees no need to raise the interest rate unless economic growth or inflation rises to a high gear. After raising the interest
2018-05-13 08:33:00 Sunday ET
Incoming New York Fed President John Williams suggests that it is about time to end forward guidance in order to stop holding the financial market's han
2018-12-29 09:32:00 Saturday ET
Andy Yeh Alpha (AYA) AYA Analytica financial health memo (FHM) podcast channel on YouTube December 2018 AYA Analytica is our online regular podcast and news
2019-09-30 07:33:00 Monday ET
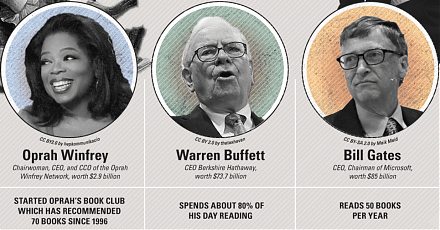
AYA Analytica finbuzz podcast channel on YouTube September 2019 In this podcast, we discuss several topical issues as of September 2019: (1) Former
2023-04-28 16:38:00 Friday ET
Peter Schuck analyzes U.S. government failures and structural problems in light of both institutions and incentives. Peter Schuck (2015) Why
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
 Reports
 Metrics
 Events

 AI Stock Synopses