Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 12 September 2026
2023-12-03 11:33:00 Sunday ET
Macro innovations and asset alphas show significant mutual causation. April 2023 This brief article draws from the recent research publicati
2025-10-06 10:27:00 Monday ET
Stock Synopsis: With a new Python program, we use, adapt, apply, and leverage each of the mainstream Gemini Gen AI models to conduct this comprehensive fund
2018-05-03 07:34:00 Thursday ET
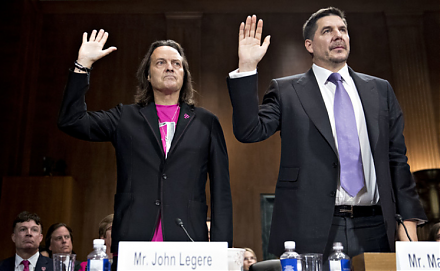
Sprint and T-Mobile propose a major merger in order to better compete with AT&T and Verizon. This mega merger is worth $26.5 billion and involves an all
2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode
2019-11-01 12:31:00 Friday ET
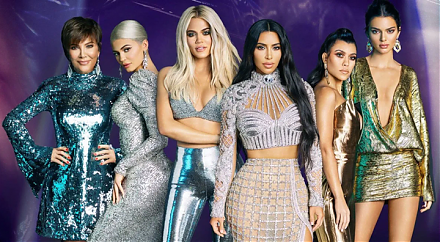
Kourtney Kardashian shares the best money advice from her father. This advice reminds her that money just cannot buy happiness. As the eldest of the Kardash
2019-02-25 12:41:00 Monday ET
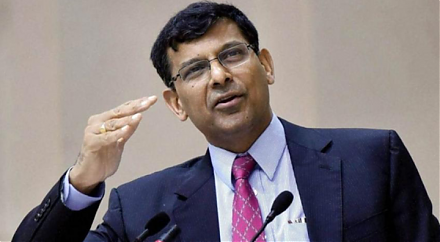
Chicago financial economist Raghuram Rajan views communities as the third pillar of liberal democracy in addition to open markets and states. Rajan suggests
 Reports
 Metrics
 Events

 AI Stock Synopses