Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 10 October 2026
2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode
2018-06-03 07:35:00 Sunday ET
Several recent events explain why Trump may undermine multilateral world order. First, Trump withdraws the U.S. from the 12-nation Trans-Pacific Partnership
2018-10-11 08:44:00 Thursday ET
Treasury bond yield curve inversion often signals the next economic recession in America. In fact, U.S. bond yield curve inversion correctly predicts the da
2017-06-09 06:37:00 Friday ET
To complement President Trump's pro-business economic policies such as low taxation, new infrastructure, greater job creation, and technological in
2018-10-07 13:39:00 Sunday ET
The U.S. greenback soars in value as the Federal Reserve continues its interest rate hike. With impressive service-sector data and non-farm payroll wage gro
2018-01-04 07:36:00 Thursday ET
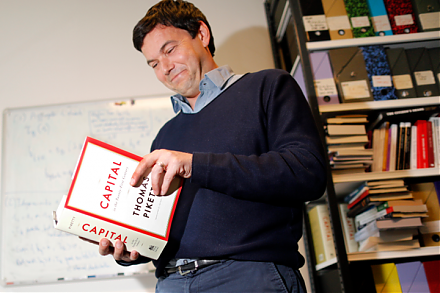
The world now faces an economic inequality crisis with few policy options. Some recent U.S. Federal Reserve data suggest that both income and wealth inequal
 Reports
 Metrics
 Events

 AI Stock Synopses