Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 10 October 2026
2017-03-09 05:32:00 Thursday ET
From 1927 to 2017, the U.S. stock market has delivered a hefty average return of about 11% per annum. The U.S. average stock market return is high in stark
2019-08-03 09:28:00 Saturday ET
U.S. inflation has become sustainably less than the 2% policy target in recent years. As Harvard macro economist Robert Barro indicates, U.S. inflation has
2019-07-05 09:32:00 Friday ET
Warwick macroeconomic expert Roger Farmer proposes paying for social welfare programs with no tax hikes. The U.S. government pension and Medicare liabilitie
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2023-04-21 12:39:00 Friday ET
Angus Deaton analyzes the correlation between health and wealth in light of the economic origins of inequality worldwide. Angus Deaton (2015)
2019-11-05 07:41:00 Tuesday ET
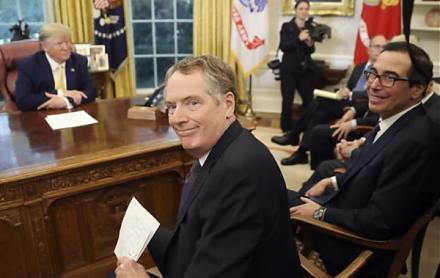
The Trump administration expects to reach an interim partial trade deal with China. This interim partial trade deal represents the first phase of a comprehe
 Reports
 Metrics
 Events

 AI Stock Synopses