
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 26 September 2026
2017-05-07 06:39:00 Sunday ET
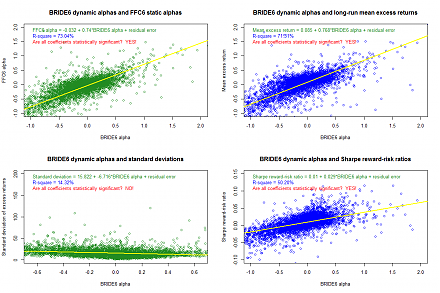
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2023-01-03 09:34:00 Tuesday ET
USPTO fintech patent protection and accreditation As of early-January 2023, the U.S. Patent and Trademark Office (USPTO) has approved
2024-04-02 04:45:41 Tuesday ET
Stock Synopsis: High-speed 5G broadband and mobile cloud telecommunication In the U.S. telecom industry for high-speed Internet connections and mobile cl
2020-07-12 08:30:00 Sunday ET
The lean CEO encourages iterative continuous improvements and collaborative teams to innovate around core value streams. Jacob Stoller (2015)
2023-09-21 09:26:00 Thursday ET
Jordi Gali delves into the science of the New Keynesian monetary policy framework with economic output and inflation stabilization. Jordi Gali (2015)
2018-04-17 12:38:00 Tuesday ET
Value investment strategies make investors wiser like water with core fundamental factor analysis. Value investors tend to buy stocks below their intrinsic
 Reports
 Metrics
 Events

 AI Stock Synopses