
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 3 October 2026
2018-06-01 07:30:00 Friday ET
The U.S. federal government debt has risen from less than 40% of total GDP about a decade ago to 78% as of May 2018. The Congressional Budget Office predict
2019-11-15 13:34:00 Friday ET
The Economist offers a special report that the new normal state of economic affairs shines fresh light on the division of labor between central banks and go
2019-09-19 15:30:00 Thursday ET
U.S. yield curve inversion can be a sign but not a root cause of the next economic recession. Treasury yield curve inversion helps predict each of the U.S.
2020-09-15 08:38:00 Tuesday ET
Macro eigenvalue volatility helps predict some recent episodes of high economic policy uncertainty, recession risk, or rare events such as the recent rampan
2019-04-30 07:15:00 Tuesday ET
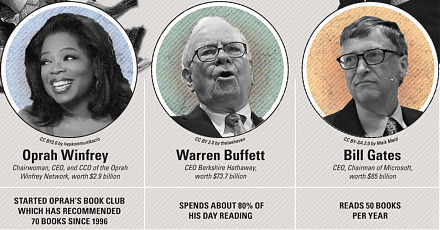
Through our AYA fintech network platform, we share numerous insightful posts on personal finance, stock investment, and wealth management. Our AYA finte
2020-11-10 07:25:00 Tuesday ET
The McKinsey edge reflects the collective wisdom of key success principles in business management consultancy. Shu Hattori (2015) The McKins
 Reports
 Metrics
 Events

 AI Stock Synopses