2019-08-22 11:35:00 Thu ET
stock market gold oil stock return s&p 500 asset market stabilization asset price fluctuations stocks bonds currencies commodities funds term spreads credit spreads fair value spreads asset investments
Fundamental factors often reflect macroeconomic innovations and so help inform better stock investment decisions. Nobel Laureate Eugene Fama and his long-time co-author Ken French empirically find that several fundamental factors help price the cross-section of average asset returns. These fundamental factors include the return spreads between the top-and-bottom stock portfolios that the analyst sorts on size, value, momentum, asset growth, profitability, and market risk exposure.
In terms of stock market capitalization, small stocks often outperform large stocks by a significant 5%-7% factor premium. Value stocks can consistently beat glamour stocks by a 7%-9% factor premium. Furthermore, investors can earn hefty average returns on stocks with high recent share price performance, low capital-intensive asset growth, high cash profitability, and low market risk exposure (beta arbitrage). AQR Capital investment practitioners show that both value and momentum factor premiums significantly persist in global asset markets. To the extent that key factor premiums exhibit mutual causation with macroeconomic surprises, this causation serves as a new condition for fundamental factor selection. As investors learn from their behavioral biases, quirks, and other investment mistakes, these investors tilt their asset portfolios toward high factor premiums. This factor investment approach helps generate consistent supernormal asset returns in the long run.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2018-02-11 07:30:00 Sunday ET
President Trump unveils his ambitious $1.5 trillion public infrastructure plan. Trump proposes offering $100 billion in federal incentives to encourage stat
2018-04-26 07:37:00 Thursday ET
Credit supply growth drives business cycle fluctuations and often sows the seeds of their own subsequent destruction. The global financial crisis from 2008
2023-12-05 09:25:00 Tuesday ET
Better corporate ownership governance through worldwide convergence toward Berle-Means stock ownership dispersion Abstract We design a model
2017-11-23 10:42:00 Thursday ET
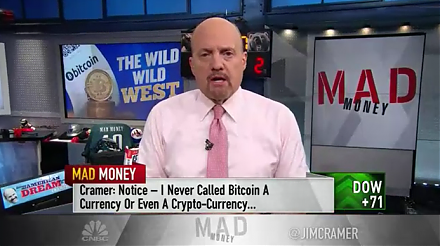
As the TV host of Mad Money, Jim Cramer provides 5 key reasons against the purchase and use of cryptocurrencies such as Bitcoin. First, no one knows the ano
2025-10-08 11:34:00 Wednesday ET
Stock Synopsis: With a new Python program, we use, adapt, apply, and leverage each of the mainstream Gemini Gen AI models to conduct this comprehensive fund
2017-04-01 06:40:00 Saturday ET
With the current interest rate hike, large banks and insurance companies are likely to benefit from higher equity risk premiums and interest rate spreads.