2018-03-21 06:32:00 Wed ET
federal reserve monetary policy treasury dollar employment inflation interest rate exchange rate macrofinance recession systemic risk economic growth central bank fomc greenback forward guidance euro capital global financial cycle credit cycle yield curve
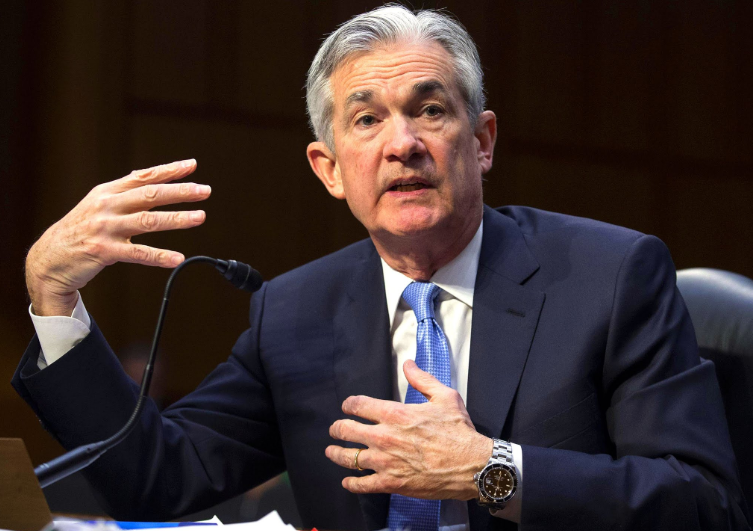
Fed Chair Jerome Powell increases the neutral interest rate to a range of 1.5% to 1.75% in his debut post-FOMC press conference. The Federal Reserve raises the interest rate for the sixth time since the Federal Open Market Committee (FOMC) near-zero rate lift-off in December 2015. The Fed Chair transition from Yellen to Powell indicates a moderate monetary policy regime switch from dovish to hawkish in accordance with the recent FOMC minutes.
The Federal Reserve now targets a core PCE inflation rate above 2.1% as the U.S. unemployment rate gradually declines to the lowest level of 3.8%-4.1% in 17 years. Most dynamic stochastic general equilibrium (DSGE) New Keynesian economic models suggest that Powell has to trade off near-full employment with inflationary momentum. As inflation picks up over time, Powell must gradually raise the neutral interest rate to tame upward price gyrations when the U.S. economy operates near full employment.
Former Fed Chair Janet Yellen might prefer to keep the lower interest rate for a longer period of time, whereas, Powell departs from this lower-for-longer dovish and accommodative monetary policy stance in response to key FOMC hawks who express deep concerns about high inflation or price instability.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2025-09-21 12:32:00 Sunday ET
Stock Synopsis: With a new Python program, we use, adapt, apply, and leverage each of the mainstream Gemini Gen AI models to conduct this comprehensive fund
2022-05-25 09:31:00 Wednesday ET
Net stock issuance theory and practice Net equity issuance can be in the form of initial public offering (IPO) or seasoned equity offering (SEO). This l
2018-10-11 08:44:00 Thursday ET
Treasury bond yield curve inversion often signals the next economic recession in America. In fact, U.S. bond yield curve inversion correctly predicts the da
2019-08-09 18:35:00 Friday ET
Nobel Laureate Joseph Stiglitz maintains that globalization only works for a few elite groups; whereas, the government should now reassert itself in terms o
2023-02-14 09:31:00 Tuesday ET
Eric Posner and Glen Weyl propose radical reforms to resolve key market design problems for better democracy and globalization. Eric Posner and Glen Weyl
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla