GenMark Diagnostics, Inc. is a molecular diagnostics company focused on developing and commercializing its proprietary eSensor(R) detection technology. The eSensor' XT-8 system is the second generation in GenMark Dx's eSensor' platform, utilizing electrochemical detection technology to detect nucleic acids on a microarray. The XT-8 System enables multiplex detection of DNA and RNA targets. The Company has developed four diagnostic tests for use with its XT-8 System. Its Cystic Fibrosis Genotyping Test, which detects pre-conception risks of cystic fibrosis, and its Warfarin Sensitivity Test, which determines an individual's ability to metabolize the oral anticoagulant warfarin, have received FDA clearance. It has also developed a Respiratory Viral Panel Test, which detects the presence of major respiratory viruses, and a Thrombosis Risk Test, which detects an individual's increased risk of blood clots. GenMark Diagnostics, Inc. is based in Pasadena, California....
+See MoreSharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 12 September 2026
2027-01-31 12:25:00 Sunday ET
In recent decades, many governments have chosen to run high fiscal deficits on top of sovereign debt mountains so that greater government intervention still
2018-07-05 13:40:00 Thursday ET
U.S. trading partners such as the European Union, Canada, China, Japan, Mexico, and Russia voice their concern at the World Trade Organization (WTO) in ligh
2026-01-31 10:31:00 Saturday ET
In recent years, several central banks conduct, assess, and discuss the core lessons, rules, and challenges from their monetary policy framework r
2018-11-11 13:42:00 Sunday ET
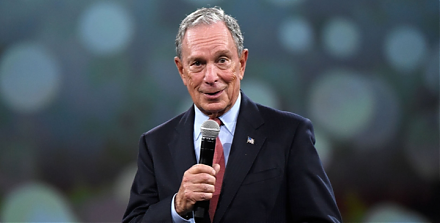
Michael Bloomberg provides $80 million as campaign finance for Democrats to flip the House of Representatives in the November 2018 midterm elections, gears
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla
2019-05-15 12:32:00 Wednesday ET
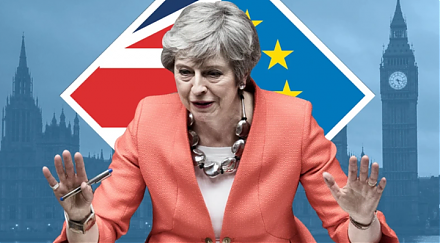
The May administration needs to seek a fresh fallback option for Halloween Brexit. After the House of Commons rejects Brexit proposals from the May administ
 Reports
 Metrics
 Events

 AI Stock Synopses