
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 10 October 2026
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2018-01-19 11:32:00 Friday ET
Most major economies grow with great synchronicity several years after the global financial crisis. These economies experience high stock market valuation,
2025-10-31 12:26:00 Friday ET
With respect to wider weight loss treatment and obesity treatment, the global market for GLP-1 medications now grows substantially to benefit more than 1 bi
2019-07-31 11:34:00 Wednesday ET
AYA Analytica finbuzz podcast channel on YouTube July 2019 In this podcast, we discuss several topical issues as of July 2019: (1) All 18 systemical
2024-02-05 11:26:00 Monday ET
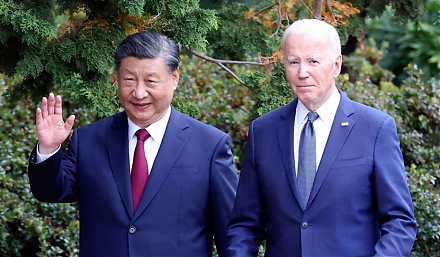
China poses new economic, technological, and military threats to the U.S. and many western allies. In the U.S. government assessment, China poses new eco
2023-11-21 11:32:00 Tuesday ET
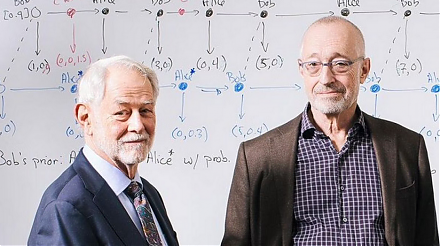
Nobel Laureate Paul Milgrom explains the U.S. incentive auction of wireless spectrum allocation from TV broadcasters to telecoms. Paul Milgrom (2019)
 Reports
 Metrics
 Events

 AI Stock Synopses