2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode
2022-04-15 10:32:00 Friday ET
Corporate investment management This review of corporate investment literature focuses on some recent empirical studies of M&A, capital investm
2018-05-06 07:30:00 Sunday ET
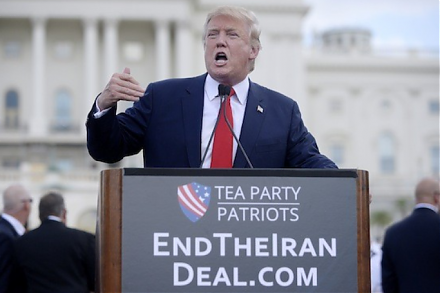
President Trump withdraws America from the Iran nuclear agreement and revives economic sanctions on Iran for better negotiations as western allies Britain,
2020-09-15 08:38:00 Tuesday ET
Macro eigenvalue volatility helps predict some recent episodes of high economic policy uncertainty, recession risk, or rare events such as the recent rampan
2024-02-04 08:28:00 Sunday ET
Our proprietary alpha investment model outperforms most stock market indexes from 2017 to 2024. Our proprietary alpha investment model outperforms the ma
2019-07-31 11:34:00 Wednesday ET
AYA Analytica finbuzz podcast channel on YouTube July 2019 In this podcast, we discuss several topical issues as of July 2019: (1) All 18 systemical