Home > Library > An empirical implementation of CreditGrades
Author Andy Yeh Alpha
This research article empirically implements the novel and non-obvious credit risk model CreditGrades.
Description:
We use the CreditGrades credit risk model to value credit default swap (CDS) spreads for public companies at the intersection of the S&P 100 index and Moody's Bottom Rung report for the global financial crisis period from 2007Q3 to 2009Q2. We implement this canonical credit risk model in accordance with the *CreditGrades technical document* jointly developed by Goldman Sachs, JP Morgan, Deutsche Bank, and RiskMetrics. Our empirical study focuses on the strengths and weaknesses of the chosen risk model by analyzing the main empirical results with several complementary statistical and qualitative tests for better triangulation.
2019-09-13 10:37:00 Friday ET
China allows its renminbi currency to slide below the key psychologically important threshold of 7-yuan per U.S. dollar. A currency dispute between the U.S.
2019-07-31 11:34:00 Wednesday ET
AYA Analytica finbuzz podcast channel on YouTube July 2019 In this podcast, we discuss several topical issues as of July 2019: (1) All 18 systemical
2025-09-13 12:23:00 Saturday ET
Stock Synopsis: With a new Python program, we use, adapt, apply, and leverage each of the mainstream Gemini Gen AI models to conduct this comprehensive fund
2019-01-01 03:34:48 Tuesday ET
American allies assist AT&T and Verizon in implementing 5G telecommunication technology in the U.S. as such allies ban the use of HuaWei 5G telecom equi
2019-08-08 09:35:00 Thursday ET
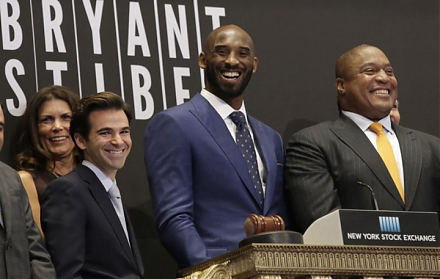
Kobe Bryant and several other star athletes have been smart savvy investors. In collaboration with former Web.com CEO Jeff Stibel, the NBA champion invests
2018-07-23 07:41:00 Monday ET
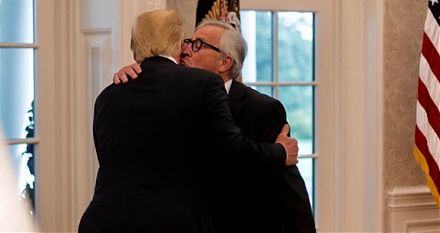
President Trump now agrees to cease fire in the trade conflict with the European Union. Both sides can work together towards *zero tariffs, zero non-tariff