2017-05-07 06:39:00 Sun ET
stock market gold oil stock return s&p 500 asset market stabilization asset price fluctuations stocks bonds currencies commodities funds term spreads credit spreads fair value spreads asset investments

While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co-author Kenneth French, the sixth factor is hypothetical in nature and stems from bullish-versus-bearish investor sentiment on social media.
In addition to the conventional fundamental factors such as size, value, market risk, operating profitability, and asset growth, the social media factor serves as a new measure of investor sentiment.
All these factors help explain the time-series variation in most U.S. stock returns relative to the risk-free rate.
Whether this additional social media factor represents exposure to systematic risk remains a debatable controversy because there is now minimal consensus on this open issue.
Several financial economists recommend raising the empirical hurdle for novel fundamental factors such as this social media measure of investor sentiment.
On balance, it is informative for most stock market investors to recognize that social media conveys pivotal information about at least part of the time variation in the vast majority of U.S. stock portfolio returns ceteris paribus.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2023-11-21 11:32:00 Tuesday ET
Nobel Laureate Paul Milgrom explains the U.S. incentive auction of wireless spectrum allocation from TV broadcasters to telecoms. Paul Milgrom (2019)
2020-02-19 14:35:00 Wednesday ET
The U.S. bank oligarchy has become bigger, more profitable, and more resistant to public regulation after the global financial crisis. Simon Johnson and
2023-07-07 10:29:00 Friday ET
Louis Kaplow strives to find a delicate balance between efficiency gains and redistributive taxes in the social welfare function. Louis Kaplow (2010)
2019-08-24 14:38:00 Saturday ET
Warren Buffett warns that the current cap ratio of U.S. stock market capitalization to real GDP seems to be much higher than the long-run average benchmark.
2018-12-11 10:34:06 Tuesday ET
Several eminent American China-specialists champion the key notion of *strategic engagement* with the Xi administration. From the Hoover Institution at Stan
2017-08-13 09:36:00 Sunday ET
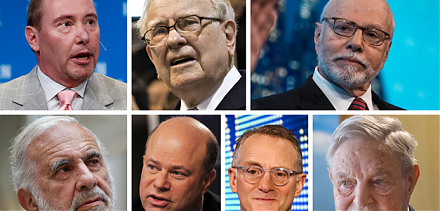
Several investors and billionaires such as George Soros, Warren Buffett, Carl Icahn, and Howard Marks suggest that the time may be ripe for a major financia