2018-09-07 07:33:00 Fri ET
stock market competition macrofinance stock return s&p 500 financial crisis financial deregulation bank oligarchy systemic risk asset market stabilization asset price fluctuations regulation capital financial stability dodd-frank
The Economist re-evaluates the realistic scenario that the world has learned few lessons of the global financial crisis from 2008 to 2009 over the past decade. Good times breed complacency. As the Trump administration rolls back key Dodd-Frank rules and regulations, the Federal Reserve has yet to raise countercyclical capital buffers for most banks. When prudence prevails, no regulator is a perfect judge of financial risk.
The Economist points out that the current news is both good and bad. The good news suggests that most U.S. large banks finance themselves with proportionately more equity. The average bank equity capital ratio increases substantially from 3% to double digits in the decade after the Lehman financial meltdown.
However, the bad news suggests that most U.S. households, firms, and financial intermediaries react slowly to the U.S. subprime mortgage crisis from 2008 to 2009.
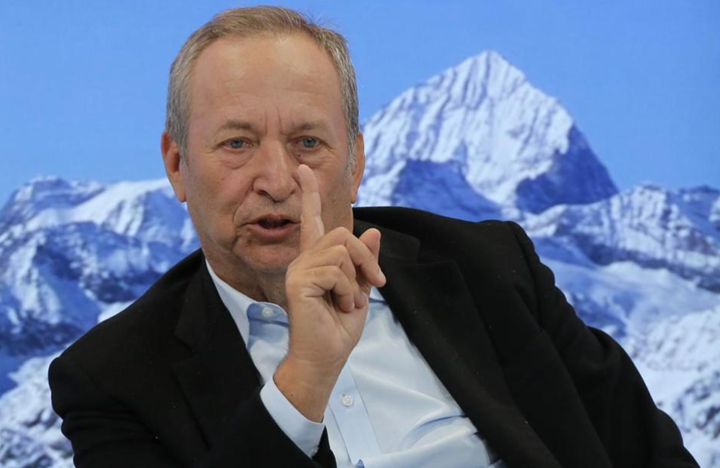
Former U.S. Treasury Secretary and Harvard President Larry Summers shares his ingenious insight that the U.S. economy suffers secular stagnation, government debt, and inflation in the recent decade after the global financial crisis. In light of gradual greenback appreciation and national populism, Harvard chair professor Kenneth Rogoff indicates that the Trump stock market rally may be the calm before the next financial storm.
Despite hefty Trump tax cuts and infrastructure expenditures, the U.S. economy operates near full employment with high inflation, currency, and interest rate risks. This trifecta poses a red alert to the Trump administration and its advisory troika (National Economic Council, Federal Reserve, and Treasury).
Both the U.S. Treasury and National Economic Council favor imposing draconian tariffs on at least $200 trillion Chinese imports. This trade tactic aims to help curtail bilateral trade deficits with China. These tariffs may affect Canada, Europe, Mexico, and Japan.
Moreover, the Federal Reserve accelerates the current interest rate hike (with at least one rate increase in September 2018 and another in December 2018). This hawkish interest rate hike is likely to continue until late-2019. All of these fiscal and monetary measures can help contain the high-risk trifecta of inflation, fiscal debt and deficit, and secular stagnation.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2018-12-20 13:40:00 Thursday ET
T-Mobile and Sprint indicate that the U.S. is likely to approve their merger plan as they take the offer from foreign owners to stop using HuaWei telecom te
2021-02-01 10:19:00 Monday ET
In recent times, the International Monetary Fund (IMF) predicts that the fiscal-debt-to-GDP ratio of most rich economies would rise from 95% in 2018 to 135%
2018-12-29 09:32:00 Saturday ET
Andy Yeh Alpha (AYA) AYA Analytica financial health memo (FHM) podcast channel on YouTube December 2018 AYA Analytica is our online regular podcast and news
2025-05-29 08:25:28 Thursday ET
Serial venture capitalist Ben Horowitz describes many hard truths, lessons, and insights from his entrepreneurial journey of running LoudCloud from a Silico
2021-08-01 07:26:00 Sunday ET
The Biden administration launches economic reforms in fiscal and monetary stimulus, global trade, finance, and technology. President Joe Biden proposes s
2023-08-07 12:29:00 Monday ET
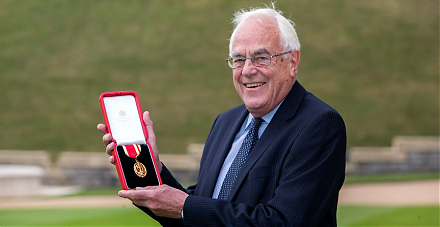
Oxford macro professor Stephen Nickell and his co-authors delve into the trade-off between inflation and unemployment in the dual mandate of price stability