2018-04-26 07:37:00 Thu ET
federal reserve monetary policy treasury dollar employment inflation interest rate exchange rate macrofinance recession systemic risk economic growth central bank fomc greenback forward guidance euro capital global financial cycle credit cycle yield curve
Credit supply growth drives business cycle fluctuations and often sows the seeds of their own subsequent destruction. The global financial crisis from 2008 to 2009 suggests that we can predict a key slowdown in real economic activity by tracking incremental household debt accumulation. In both America and 30 other countries, changes in household debt-to-GDP ratios from 2002 to 2007 significantly correlate with increases in unemployment from 2007 to 2010.
From this empirical perspective, credit supply expansions, rather than permanent income or technology shocks, serve as a major driver of real business cycles over time. Most macro models attribute macroeconomic fluctuations to real factors such as exogenous productivity shocks. In contrast, financial intermediaries can play an important role in aggregate credit supply growth, household leverage, employment, and asset valuation. Credit supply expansions affect the real economy by boosting household demand, rather than the productive capacity of firms.
In fact, credit booms tend to precede higher inflation and employment in retail and construction (but not in the tradable or export-driven business sector). The key real economy slowly adjusts to the precipitous decrease in consumer expenditures due to high household leverage when credit supply slows down in major financial crises.
Even when short-term interest rates decline to zero, savers cannot spend enough to make up for the shortfall in aggregate demand. Also, employment cannot readily gravitate from the non-tradable sector to the tradable sector. Key nominal rigidities, sluggish price adjustments, and other legacy distortions render post-credit-boom recessions more severe. What triggers credit supply growth involves a major influx of capital in the financial system.
In this light, both monetary and fiscal stimulus can have a major impact on the real economy via credit supply growth, household debt, stock and bond prices, and real business cycles. Overall, financial stability serves as a core precondition for better bond and stock valuation.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2017-11-17 09:42:00 Friday ET
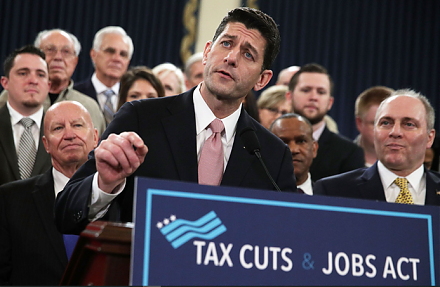
The Trump administration garners congressional support from both Senate and the House of Representatives to pass the $1.5 trillion tax overhaul (Tax Cuts &a
2018-08-23 11:34:00 Thursday ET
Harvard financial economist Alberto Cavallo empirically shows the recent *Amazon effect* that online retailers such as Amazon, Alibaba, and eBay etc use fas
2018-03-25 08:39:00 Sunday ET
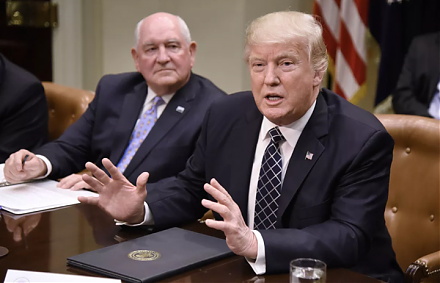
President Trump imposes punitive tariffs on $60 billion Chinese imports in a brand-new trade war as China hits back with retaliatory tariffs on $3 billion U
2018-11-19 09:38:00 Monday ET
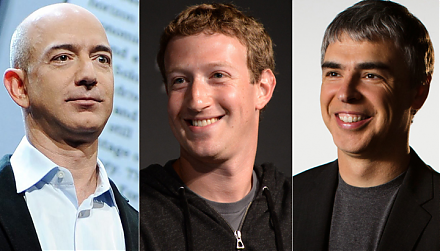
The Trump administration mulls over antitrust actions against Amazon, Facebook, and Google. President Trump indicates that the $5 billion fine against Googl
2018-12-05 09:38:00 Wednesday ET
Federal Reserve publishes its inaugural flagship financial stability report. Fed Chair Jerome Powell applauds both low inflation (2%) and low unemployment (
2018-07-17 08:35:00 Tuesday ET
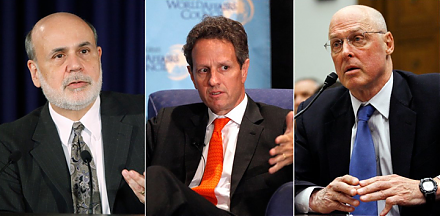
Henry Paulson and Timothy Geithner (former Treasury heads) and Ben Bernanke (former Fed chairman) warn that people seem to have forgotten the lessons of the