Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 17 October 2026
2025-05-29 08:25:28 Thursday ET
Serial venture capitalist Ben Horowitz describes many hard truths, lessons, and insights from his entrepreneurial journey of running LoudCloud from a Silico
2020-08-12 07:25:00 Wednesday ET
Most sustainably successful business leaders make a mark in the world, create a positive impact, and challenge the status quo. Jerry Porras, Stewart Emer
2022-09-25 09:34:00 Sunday ET
Main reasons for share repurchases Temporary market undervaluation often induces corporate incumbents to initiate a share repurchase program to boost the
2018-05-07 07:32:00 Monday ET
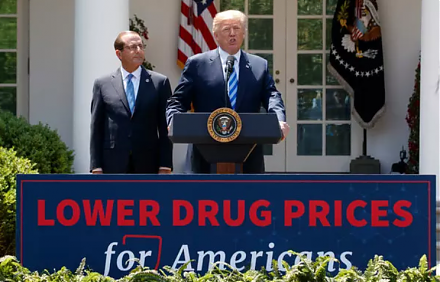
President Trump seeks to honor his campaign promise of lower U.S. medical costs by forcing higher big-pharma prices in foreign countries such as Canada, Bri
2023-04-28 16:38:00 Friday ET
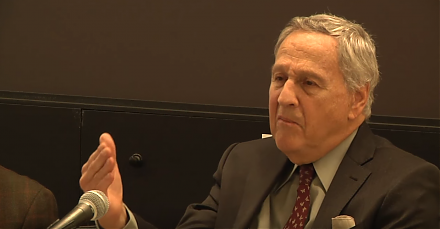
Peter Schuck analyzes U.S. government failures and structural problems in light of both institutions and incentives. Peter Schuck (2015) Why
2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode
 Reports
 Metrics
 Events

 AI Stock Synopses