Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 26 September 2026
2023-05-27 11:30:00 Saturday ET
Bank failure resolution and financial risk management: Silicon Valley Bank, Signature Bank, and First Republic Bank. What are the main root cau
2019-08-05 13:30:00 Monday ET
China continues to sell U.S. Treasury bonds amid Sino-U.S. trade truce uncertainty. In mid-2019, China reduces its U.S. Treasury bond positions by $20.5 bil
2016-11-08 00:00:00 Tuesday ET
Donald Trump defies the odds to become the new U.S. president. He wants to make America great again. He seeks to repeal Obamacare. He has zero tole
2019-04-07 13:39:00 Sunday ET
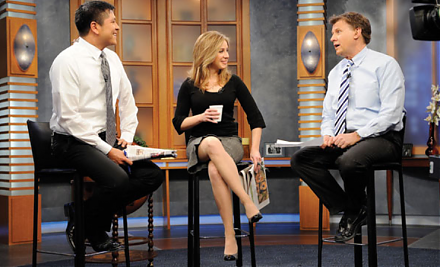
CNBC news anchor Becky Quick interviews Warren Buffett in early-2019. Buffett explains the fact that book value fluctuations are a metric that has lost rele
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2018-08-19 10:34:00 Sunday ET
The World Economic Forum warns that artificial intelligence may destabilize the financial system. Artificial intelligence poses at least a trifecta of major
 Reports
 Metrics
 Events

 AI Stock Synopses