Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 12 September 2026
2018-01-21 07:25:00 Sunday ET
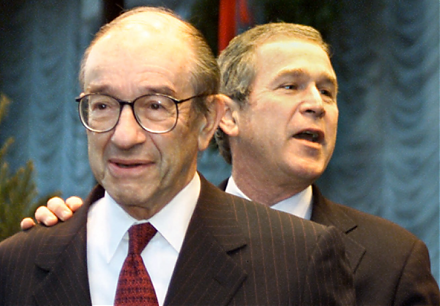
As he refrains from using the memorable phrase *irrational exuberance* to assess bullish investor sentiments, former Fed chairman Alan Greenspan discerns as
2019-03-31 11:40:00 Sunday ET
AYA Analytica free finbuzz podcast channel on YouTube March 2019 In this podcast, we discuss several topical issues as of March 2019: (1) Sargent-Wallac
2020-08-26 10:33:00 Wednesday ET
Through purposeful leadership, senior managers inspire teams to reach heights of both innovation and profitability with great brand identity and customer lo
2023-09-07 11:30:00 Thursday ET
Michael Woodford provides the theoretical foundations of monetary policy rules in ever more efficient financial markets. Michael Woodford (2003)
2019-01-19 12:38:00 Saturday ET
U.S. government shuts down again because House Democrats refuse to spend $5 billion on the border wall that would give President Trump great victory on his
2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode
 Reports
 Metrics
 Events

 AI Stock Synopses