
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 26 September 2026
2017-09-19 05:34:00 Tuesday ET
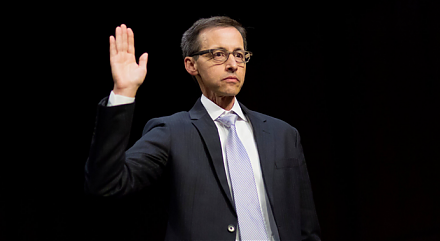
Facebook, Twitter, and Google executives head before the Senate Judiciary Committee to explain the scope of Russian interference in the U.S. presidential el
2025-07-01 13:35:00 Tuesday ET
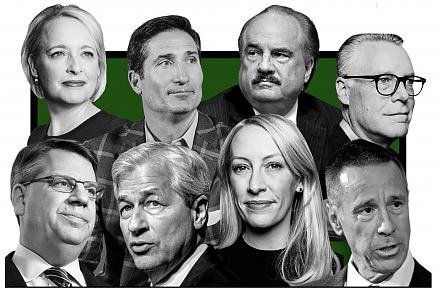
In recent times, financial deglobalization and asset market fragmentation can cause profound public policy implications for trade, finance, and technology w
2019-01-03 10:38:00 Thursday ET
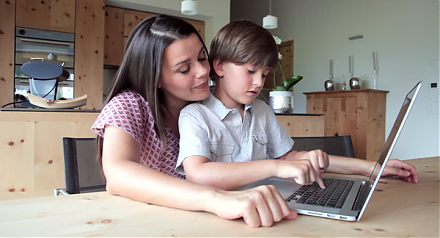
American parents often worry about money and upward mobility for their children. A recent New York Times survey suggests that nowadays American parents spen
2019-04-09 11:29:00 Tuesday ET
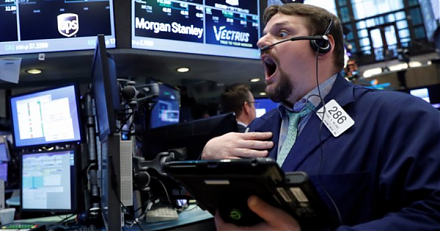
The U.S. Treasury yield curve inverts for the first time since the Global Financial Crisis. The key term spread between the 10-year and 3-month U.S. Treasur
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2020-10-06 09:31:00 Tuesday ET
Strategic managers envision lofty purposes to enjoy incremental consistent progress over time. Allison Rimm (2015) The joy of strategy: a bu
 Reports
 Metrics
 Events

 AI Stock Synopses