Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 12 September 2026
2020-11-24 09:30:00 Tuesday ET
Many analytic business competitors can apply smart data science to support their distinctive capabilities and strategic advantages. Thomas Davenport and
2017-05-13 07:28:00 Saturday ET
America's Top 5 tech firms, Apple, Alphabet, Microsoft, Amazon, and Facebook have become the most valuable publicly listed companies in the world. These
2027-04-30 12:31:00 Friday ET
In recent years, the current AI-driven stock market rally may or may not turn out to be another major asset bubble in global human history. For the pract
2019-08-31 14:39:00 Saturday ET
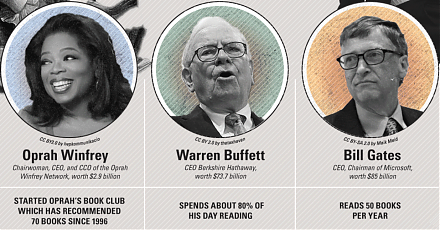
AYA Analytica finbuzz podcast channel on YouTube August 2019 In this podcast, we discuss several topical issues as of August 2019: (1) Warren B
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla
2020-09-24 10:26:00 Thursday ET
Edge strategies help business leaders improve core products and services in a more cost-effective and less risky way. Alan Lewis and Dan McKone (2016)
 Reports
 Metrics
 Events

 AI Stock Synopses