Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 17 October 2026
2019-02-21 12:37:00 Thursday ET
Apple shakes up senior leadership to initiate a new transition from iPhone revenue reliance to media and software services. These changes include the key pr
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla
2019-05-21 12:37:00 Tuesday ET
Chicago finance professor Raghuram Rajan shows that free markets need populist support against an unholy alliance of private-sector and state elites. When a
2019-10-27 17:37:00 Sunday ET
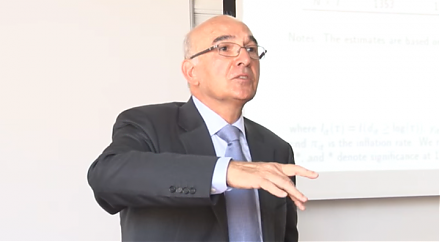
International climate change can cause an adverse impact on long-term real GDP economic growth. USC climate change economist Hashem Pesaran and his co-autho
2019-01-17 10:41:00 Thursday ET
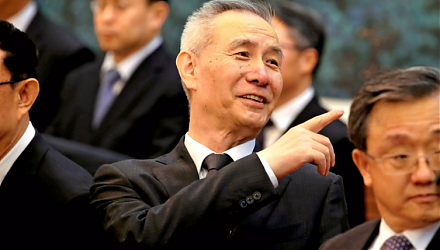
Sino-American trade talks make positive progress over 3 consecutive days as S&P 500 and global stock market indices post 3-day win streaks. Asian and Eu
2022-08-30 10:32:00 Tuesday ET
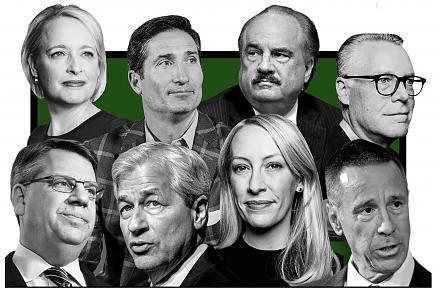
The financial services industry needs fewer banks worldwide. As long as banks have existed in human history, their managers have realized how not all dep
 Reports
 Metrics
 Events

 AI Stock Synopses