
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 26 September 2026
2018-06-03 07:35:00 Sunday ET
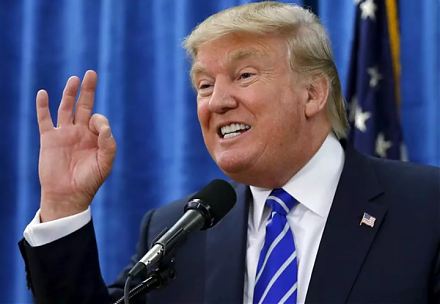
Several recent events explain why Trump may undermine multilateral world order. First, Trump withdraws the U.S. from the 12-nation Trans-Pacific Partnership
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2023-12-03 11:33:00 Sunday ET
Macro innovations and asset alphas show significant mutual causation. April 2023 This brief article draws from the recent research publicati
2017-11-27 07:39:00 Monday ET
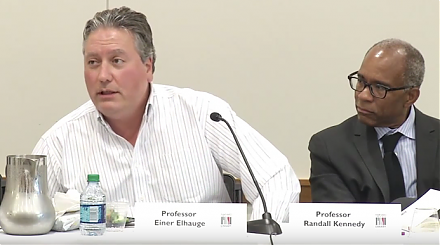
Is it anti-competitive and illegal for passive indexers and mutual funds to place large stock bets in specific industries with high market concentration? Ha
2022-11-25 09:29:00 Friday ET
Uniform field theory of corporate finance While the agency and precautionary-motive stories are complementary, these stories can be nested as special cas
2018-05-04 06:29:00 Friday ET
Commerce Secretary Wilbur Ross suggests that 5G remains a U.S. top technology priority in light of the telecom merger proposal between Sprint and T-Mobile a
 Reports
 Metrics
 Events

 AI Stock Synopses