Home > Library > Algorithmic credit portfolio segmentation
Author Andy Yeh Alpha
This research article proposes a new algorithmic model for credit portfolio segmentation.
Description:
Under the new Basel bank capital framework, each bank must group its retail exposures into multiple segments with homogeneous risk characteristics. The U.S. regulatory agencies believe that each bank may use its internal risk models for the loan-level risk parameter estimates such as probability of default (PD) and loss given default (LGD) to group individual exposures into the resultant segments with homogeneous risk attributes. In stark contrast to the conventional decision-tree method, we propose a new algorithmic technique for retail consumer loan portfolio segmentation. This new technique identifies the optimal number of segments, sorts the individual loan exposures into the various segments, and then leads to the minimal degree of risk heterogeneity in comparison to the baseline equal-bin and quantile-bin schemes. Furthermore, we analyze the Monte Carlo implicit asset correlation values for the retail loan segments over time to help assess the implications for bank capital measurement. The best-fit method for retail credit portfolio segmentation results in some capital relief that serves as an economic incentive for the bank to invest in this alternative segmentation. This positive outcome accords with the core principle of statistical conservatism that the financial econometrician enshrines in the Basel regulatory requirements for bank capital measurement.
2019-11-11 09:36:00 Monday ET
Apple upstream semiconductor chipmaker TSMC boosts capital expenditures to $15 billion with almost 10% revenue growth by December 2019. Due to high global d
2025-09-21 12:32:00 Sunday ET
Stock Synopsis: With a new Python program, we use, adapt, apply, and leverage each of the mainstream Gemini Gen AI models to conduct this comprehensive fund
2018-12-20 13:40:00 Thursday ET
T-Mobile and Sprint indicate that the U.S. is likely to approve their merger plan as they take the offer from foreign owners to stop using HuaWei telecom te
2020-02-02 10:31:00 Sunday ET
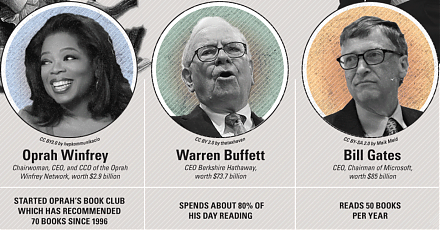
Our proprietary alpha investment model outperforms the major stock market benchmarks such as S&P 500, MSCI, Dow Jones, and Nasdaq. We implement
2019-07-03 11:35:00 Wednesday ET
U.S. regulatory agencies may consider broader economic issues in their antitrust probe into tech titans such as Amazon, Apple, Facebook, and Google etc. Hou
2020-08-05 08:33:00 Wednesday ET
Business leaders often think from a systemic perspective, share bold visions, build great teams, and learn new business models. Peter Senge (2006) &nb