2019-10-27 17:37:00 Sun ET
treasury deficit debt employment inflation interest rate macrofinance fiscal stimulus economic growth fiscal budget public finance treasury bond treasury yield sovereign debt sovereign wealth fund tax cuts government expenditures

International climate change can cause an adverse impact on long-term real GDP economic growth. USC climate change economist Hashem Pesaran and his co-authors analyze a panel dataset of 174 countries for the years from 1960 to 2014. The major empirical punchline suggests that persistent changes in the temperature above or below its historical norm cause per-capita real economic output growth ceteris paribus. Specifically, a persistent increase in average global temperature by 0.04°C reduces global real GDP per capita by at least 7.22% by 2100 once the econometrician controls for all other relevant covariates and endogenous effects.
However, if all the sample countries abide by the Paris climate agreement to limit the temperature increase to 0.01°C per annum, this climate policy coordination can lower the economic output loss substantially to no more than 1.07%. Canada, India, Japan, New Zealand, Switzerland, and the U.S. can experience 10% larger losses of economic output growth. Also, climate change can cause a long-term adverse impact on economic output, labor productivity, and employment across at least 48 U.S. states and industrial sectors for the period from 1963 to 2016. This landmark study confirms and corroborates the progressive agenda that climate change can cause a first-order adverse impact on economic consequences.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2018-12-07 11:35:00 Friday ET
Fed Chair Jerome Powell hints slower interest rate increases because the current rate is just below the neutral threshold. NYSE and NASDAQ share prices rebo
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla
2018-10-13 10:44:00 Saturday ET
Dow Jones tumbles 3% or 831 points while NASDAQ tanks 4%, and this negative investor sentiment rips through most European and Asian stock markets in early-O
2018-10-21 14:40:00 Sunday ET
President Trump floats generous 10% tax cuts for the U.S. middle class ahead of the November 2018 mid-term elections. Republican senators, congressmen, and
2019-10-29 13:36:00 Tuesday ET
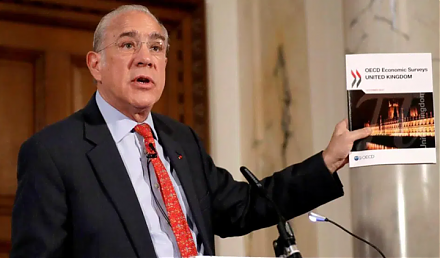
The OECD projects global growth to decline from 3.2% to 2.9% in the current fiscal year 2019-2020. This global economic growth projection represents the slo
2022-04-05 17:39:00 Tuesday ET
Corporate diversification theory and evidence A recent strand of corporate diversification literature spans at least three generations. The first generat