Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 10 October 2026
2019-06-07 04:02:05 Friday ET
The world seeks to reduce medicine prices and other health care costs to better regulate big pharma. Nowadays the Trump administration requires pharmaceutic
2021-02-01 10:19:00 Monday ET
In recent times, the International Monetary Fund (IMF) predicts that the fiscal-debt-to-GDP ratio of most rich economies would rise from 95% in 2018 to 135%
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla
2018-08-21 11:40:00 Tuesday ET
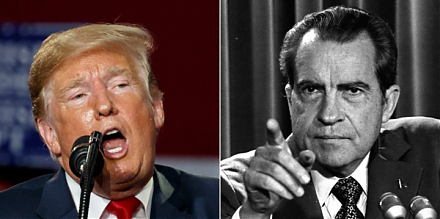
President Trump criticizes his new Fed Chair Jerome Powell for accelerating the current interest rate hike with greenback strength. This criticism overshado
2018-09-23 08:37:00 Sunday ET
Bank of America Merrill Lynch's chief investment strategist Michael Hartnett points out that U.S. corporate debt (not household credit supply or bank ca
2022-08-30 10:32:00 Tuesday ET
The financial services industry needs fewer banks worldwide. As long as banks have existed in human history, their managers have realized how not all dep
 Reports
 Metrics
 Events

 AI Stock Synopses