
N/A...
+See MoreSharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 3 October 2026
2020-09-03 10:26:00 Thursday ET
Agile business firms beat the odds by building faster institutional reflexes to anticipate plausible economic scenarios. Christopher Worley, Thomas Willi
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2019-10-13 16:22:00 Sunday ET
Apple unveils 3 iPhone 11 models with new original video services and stars such as Oprah Winfrey, Jennifer Aniston, and Reese Witherspoon. Apple releases t
2023-08-07 12:29:00 Monday ET
Oxford macro professor Stephen Nickell and his co-authors delve into the trade-off between inflation and unemployment in the dual mandate of price stability
2023-06-28 09:29:00 Wednesday ET
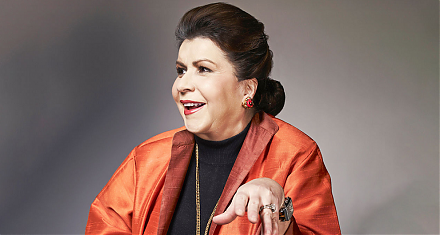
Carmen Reinhart and Kenneth Rogoff delve into several centuries of cross-country crisis data to find the key root causes of financial crises for asset marke
2018-07-30 11:36:00 Monday ET
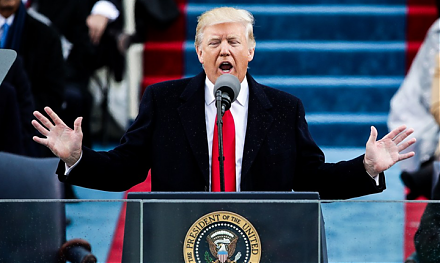
Trumpism may now become the new populist world order of economic governance. Populist support contributes to Trump's 2016 presidential election victory
 Reports
 Metrics
 Events

 AI Stock Synopses