
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 26 September 2026
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2025-01-31 09:26:00 Friday ET
The current homeland industrial policy stance worldwide seeks to embed the new notion of global resilience into economic statecraft. In the broader cont
2024-05-05 10:31:00 Sunday ET

Stock Synopsis: Pharmaceutical post-pandemic patent development cycle In terms of stock market valuation, the major pharmaceutical sector remains at its
2019-01-03 10:38:00 Thursday ET
American parents often worry about money and upward mobility for their children. A recent New York Times survey suggests that nowadays American parents spen
2018-10-23 12:36:00 Tuesday ET
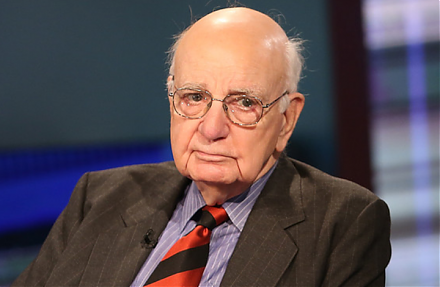
Former Fed Chair Paul Volcker releases his memoir, talks about American public governance, and worries about plutocracy in America. Volcker suggests that pu
2020-01-08 08:25:00 Wednesday ET
Conservative Party wins the British parliamentary majority in the general election with hefty British pound appreciation. In response to this general electi
 Reports
 Metrics
 Events

 AI Stock Synopses