
Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 3 October 2026
2023-11-07 11:31:00 Tuesday ET
Joel Mokyr suggests that economic growth arises from a change in cultural beliefs toward technological progress. Joel Mokyr (2018) A culture
2017-05-07 06:39:00 Sunday ET
While the original five-factor asset pricing model arises from a quasi-lifetime of top empirical research by Nobel Laureate Eugene Fama and his long-time co
2019-05-23 10:33:00 Thursday ET
Berkeley professor and economist Barry Eichengreen reconciles the nominal and real interest rates to argue in favor of greater fiscal deficits. French econo
2023-08-07 12:29:00 Monday ET
Oxford macro professor Stephen Nickell and his co-authors delve into the trade-off between inflation and unemployment in the dual mandate of price stability
2019-10-09 16:46:00 Wednesday ET
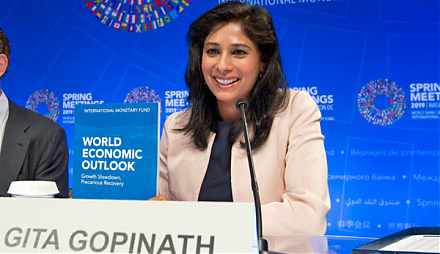
IMF chief economist Gita Gopinath indicates that competitive currency devaluation may be an ineffective solution to improving export prospects. In the form
2018-11-15 12:35:00 Thursday ET
Warren Buffett approves Berkshire Hathaway to implement new meaningful stock repurchases. Buffett sends a positive signal to the stock market with the Berks
 Reports
 Metrics
 Events

 AI Stock Synopses