Home > Library > Credit default swaps and interest rate innovations
Author Andy Yeh Alpha
This research article empirically shows the mysterious and inexorable nexus between credit default swap spreads and interest rate surprises.
Description:
This paper examines the empirical relationship between credit risk and interest rate risk. We use the credit default swap (CDS) spread as our measure of credit risk. Also, we control for the variation in the fair-value spread that combines multiple sources of default risk, including the market price of risk (Sharpe ratio), the loss given default (LGD), and the expected default frequency (EDF). After taking into account the fair-value spread, a liquidity risk factor, and several proxies for the general state of the macroeconomy, we find that the interest rate surprise factor serves as a robust determinant of CDS spread gyrations in both the full sample and most subsamples organized by industry type and credit rating status. Furthermore, we empirically find that the swap interest rate variables convey material information about CDS spread movements above and beyond the Treasury interest rate variables in the vast majority of 2SLS regressions. These empirical results have important implications for the parameterization of interest rate dynamics in the Monte Carlo simulation of economic capital for a typical bank's credit portfolio.
2019-07-29 11:33:00 Monday ET
Blackrock asset research director Andrew Ang shares his economic insights into fundamental factors for global asset management. As Ang indicates in an inter
2021-11-22 11:29:00 Monday ET
U.S. judiciary subcommittee delves into the market dominance of online platforms in terms of the antitrust, commercial, and administrative law in America.
2023-12-08 08:28:00 Friday ET
Tax policy pluralism for addressing special interests Economists often praise as pluralism the interplay of special interest groups in public policy. In
2019-04-07 13:39:00 Sunday ET
CNBC news anchor Becky Quick interviews Warren Buffett in early-2019. Buffett explains the fact that book value fluctuations are a metric that has lost rele
2023-04-21 12:39:00 Friday ET
Angus Deaton analyzes the correlation between health and wealth in light of the economic origins of inequality worldwide. Angus Deaton (2015)
2017-04-07 15:34:00 Friday ET
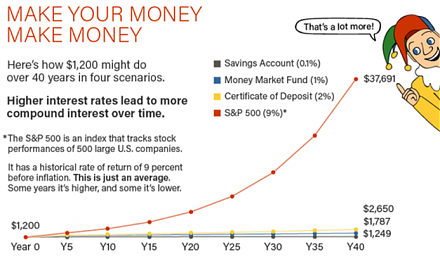
Would you rather receive $1,000 each day for one month or a magic penny that doubles each day over the same month? At first glance, this counterintuitive