2019-07-29 11:33:00 Mon ET
stock market competition macrofinance stock return s&p 500 financial crisis financial deregulation bank oligarchy systemic risk asset market stabilization asset price fluctuations regulation capital financial stability dodd-frank
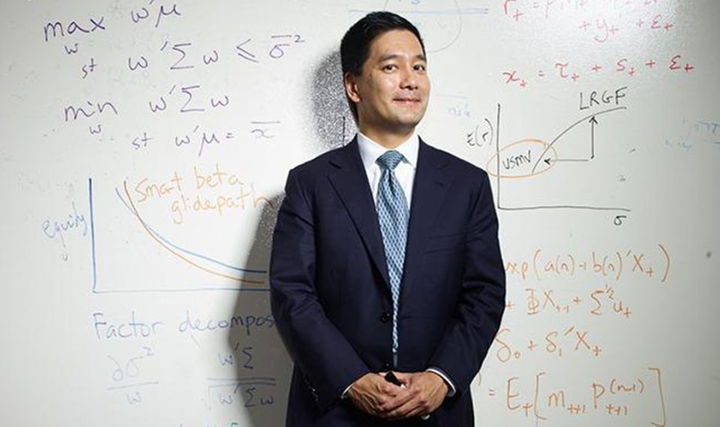
Blackrock asset research director Andrew Ang shares his economic insights into fundamental factors for global asset management. As Ang indicates in an interview with Ritholtz Wealth Management, fundamental factor investors seek to manage macroeconomic risk to enhance their average returns. Ang focuses on 5 primary factors: size, value, momentum, low volatility, and high quality of profit margins. In addition, Ang oversees a broad basket of assets such as stocks, bonds, currencies, and commodities.
The consistent application of both big data and technology helps scale total assets under management with lower transaction costs. At BlackRock, Ang decomposes his favorite fundamental factors across macro and style factors. The 3 major macro factors are *economic growth, inflation, and the real interest rate*, in accordance with the baseline Taylor interest rate that depicts a highly non-linear Phillips curve. Ang empirically finds that these 3 macroeconomic factors account for 85% of stock market returns. Stock portfolio analysis helps achieve higher average returns (after risk and fee adjustments) when the active fund manager focuses on size, value, momentum, low volatility, and corporate profitability. Moreover, value occasionally becomes more cost-effective relative to its own history, and key momentum returns often cluster together in specific time periods. This factor investment methodology accords with our proprietary alpha investment model that relies on 6 fundamental factors (size, value, momentum, asset growth, operating profitability, and market risk exposure).
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2027-11-22 08:26:00 Monday ET
Our AYA fun podcasts deep-dive into the current global trends, topics, and issues in macro finance, political economy, public policy, strategic management,
2023-08-14 09:25:00 Monday ET
Peter Isard analyzes the proper economic policy reforms and root causes of global financial crises of the 1990s and 2008-2009. Peter Isard (2005) &nbs
2019-12-25 19:46:00 Wednesday ET
Former White House chief economic advisor Nouriel Roubini discusses the major limits of central-bank-driven fiscal deficits. The International Monetary Fund
2019-09-19 15:30:00 Thursday ET
U.S. yield curve inversion can be a sign but not a root cause of the next economic recession. Treasury yield curve inversion helps predict each of the U.S.
2023-06-07 10:27:00 Wednesday ET
Anat Admati and Martin Hellwig raise broad critical issues about bank capital regulation and asset market stabilization. Anat Admati and Martin Hellwig (
2019-04-09 11:29:00 Tuesday ET
The U.S. Treasury yield curve inverts for the first time since the Global Financial Crisis. The key term spread between the 10-year and 3-month U.S. Treasur