2019-08-30 11:35:00 Fri ET
trust perseverance resilience empathy compassion passion purpose vision mission life metaphors seamless integration critical success factors personal finance entrepreneur inspiration grit

The conventional wisdom suggests that chameleons change their skin coloration to camouflage their presence for survival through Darwinian biological evolution. This naive intuition seems so natural and nomological that most people assume so on the basis of common sense. However, scientific research demonstrates that chameleons run much faster than their predators. This fresh insight causes many scientists to view camouflage as part of the story for this functional skin coloration. More recent research suggests that chameleons typically vary their skin coloration to express key social signals in response to other chameleons, external conditions, and physiological changes. For instance, bright skin color signals an aggressive emotion while dark skin color reflects a submissive reaction.
Overall, scientific research trumps basic intuition and common sense. The same idea applies to the economic science of dynamic asset management too. We often need to learn from fundamental factors in order to decipher economic insights into how macroeconomic fluctuations manifest in the cross-section of average asset returns. These fundamental factors include the return spreads between the top-to-bottom 30% of stocks for size, value, momentum, asset growth, cash profitability, and market risk exposure. Our proprietary alpha investment algorithm serves this fundamental purpose.
If any of our AYA Analytica financial health memos (FHM), blog posts, ebooks, newsletters, and notifications etc, or any other form of online content curation, involves potential copyright concerns, please feel free to contact us at service@ayafintech.network so that we can remove relevant content in response to any such request within a reasonable time frame.
2023-12-04 12:30:00 Monday ET
Bank leverage and capital bias adjustment through the macroeconomic cycle Abstract We assess the quantitative effects of the recent proposal
2019-01-23 11:32:00 Wednesday ET
Higher public debt levels, global interest rate hikes, and subpar Chinese economic growth rates are the major risks to the world economy from 2019 to 2020.
2019-01-21 10:37:00 Monday ET
Andy Yeh Alpha (AYA) AYA Analytica financial health memo (FHM) podcast channel on YouTube January 2019 In this podcast, we discuss several topical issues
2018-07-30 11:36:00 Monday ET
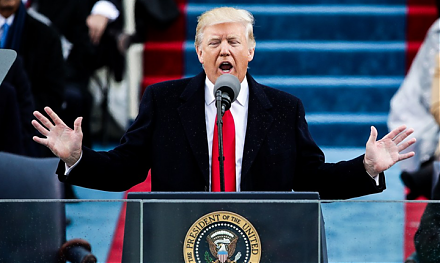
Trumpism may now become the new populist world order of economic governance. Populist support contributes to Trump's 2016 presidential election victory
2019-08-22 11:35:00 Thursday ET
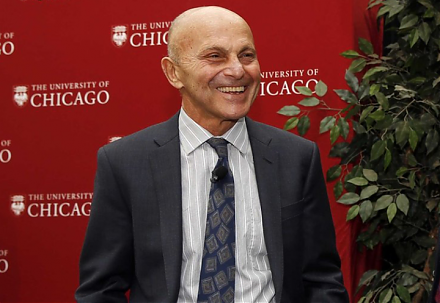
Fundamental factors often reflect macroeconomic innovations and so help inform better stock investment decisions. Nobel Laureate Eugene Fama and his long-ti
2022-03-05 09:27:00 Saturday ET
Addendum on empirical tests of multi-factor models for asset return prediction Fama and French (2015) propose an empirical five-factor asset pricing mode