Sharpe-Lintner-Black CAPM alpha (Premium Members Only) Fama-French (1993) 3-factor alpha (Premium Members Only) Fama-French-Carhart 4-factor alpha (Premium Members Only) Fama-French (2015) 5-factor alpha (Premium Members Only) Fama-French-Carhart 6-factor alpha (Premium Members Only) Dynamic conditional 6-factor alpha (Premium Members Only) Last update: Saturday 10 October 2026
2022-04-15 10:32:00 Friday ET
Corporate investment management This review of corporate investment literature focuses on some recent empirical studies of M&A, capital investm
2017-03-27 06:33:00 Monday ET
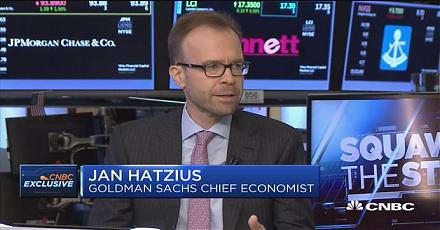
Goldman Sachs chief economist Jan Hatzius says the Federal Reserve's QE exit strategy makes sense ahead of Fed Chair Janet Yellen's stepdown in 2018
2019-09-07 17:37:00 Saturday ET
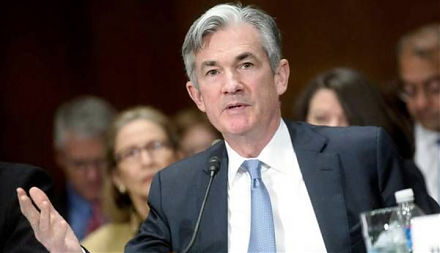
Federal Reserve Chair Jerome Powell announces the monetary policy decision to lower the federal funds rate by a quarter point to 2%-2.25%. This interest rat
2019-02-28 20:44:00 Thursday ET
AYA Analytica finbuzz podcast channel on YouTube February 2019 In this podcast, we discuss several topical issues as of February 2019: (1) our proprieta
2018-03-03 11:37:00 Saturday ET
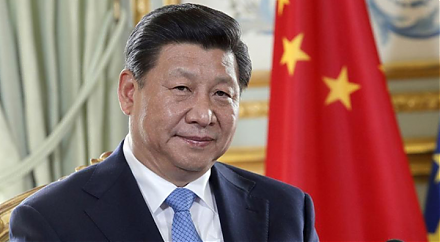
President Xi seeks Chinese congressional approval and constitutional amendment for abolishing his term limits of strongman rule with more favorable trade de
2022-02-25 00:00:00 Friday ET
Empirical tests of multi-factor models for asset return prediction The capital asset pricing model (CAPM) of Sharpe (1964), Lintner (1965), and Bla
 Reports
 Metrics
 Events

 AI Stock Synopses